We help property investors build their portfolio with the right loan structure, competitive rates and strategies that support long-term growth.
Serving eastern & south-eastern Melbourne suburbs
Not a call centre
Transparent advice every step of the way
Whether you’re buying your first investment property or adding to an existing portfolio, we’ll be with you the whole way. We explain everything clearly, help you understand your borrowing position and work to get you into the right loan structure for your investment goals.
We’ll help you move forward with clarity and confidence.
We learn about your goals, experience and portfolio plans.
We review your borrowing power, equity and lending strategy.
We compare options from 30+ lenders to suit your investment strategy.
We guide you through pre-approval and next steps.
We help you settle and support your portfolio as it grows.
Your borrowing capacity depends on your income, living expenses, existing loans and other debts, credit limits, dependants and the lender’s assessment criteria.
For an investment property, lenders may also consider expected rental income, although they generally only use a portion of it when assessing your application.
Because lending criteria vary, we can review your circumstances and help you understand your likely borrowing position before you start seriously looking for a property.
The deposit you need will depend on the property, lender and your financial circumstances. A larger deposit generally reduces your loan-to-value ratio (LVR) and may give you access to a wider range of lending options.
If you already own property, you may also be able to use available equity towards your next purchase rather than funding the entire deposit from savings.
We’ll help you understand how much you may need and the options available based on your circumstances.
Potentially, yes. If your property has increased in value or you’ve paid down your existing home loan, you may have equity that could be accessed to help fund another property purchase.
The amount you may be able to access depends on your property’s value, existing loan balance, borrowing capacity and the lender’s requirements.
We can help you work through the numbers and explain how using equity could work in your situation.
Rental income can generally be included when a lender assesses your borrowing capacity for an investment property.
However, lenders typically don’t count 100% of the expected rent. The percentage they accept and the way they assess your other income and commitments can also vary between lenders.
This is one reason your borrowing capacity can differ considerably from one lender to another.
Not necessarily. Having your loans with one lender can be convenient, but your existing bank won’t always offer the most suitable option for your next property.
Different lenders have different interest rates, features, lending policies and ways of assessing borrowing capacity.
We’ll look at your overall position and compare suitable options rather than automatically placing your investment loan with your existing lender.
It can be worth reviewing your existing loans before purchasing another property. Refinancing may provide an opportunity to access equity, change your lending arrangements or move to a more suitable loan.
However, refinancing isn’t automatically the right choice. There may be fees, costs and other considerations involved.
We can review your existing lending alongside your plans for the next property and help you understand the available finance options.
Pre-approval can give you a clearer idea of your borrowing position and potential price range before you start making offers.
It can also mean you’re better prepared to move when you find a suitable property. However, pre-approval is generally conditional and isn’t a guarantee that a lender will approve a particular property or provide final approval.
We’ll explain the conditions and help you understand what needs to happen once you’ve found the property you want to purchase.
Whether you’re planning your first investment or your next one, let’s look at your borrowing position and finance options.
Mon - Fri, 9:00am - 5:30pm AEST
Local mortgage advisers. Plain English. Better outcomes.
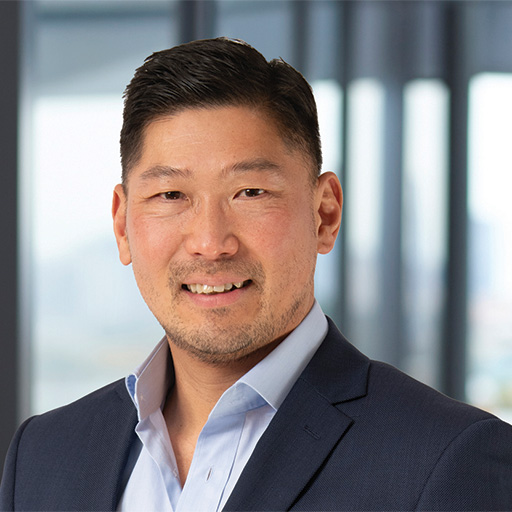
Director & Mortgage/ Credit Adviser
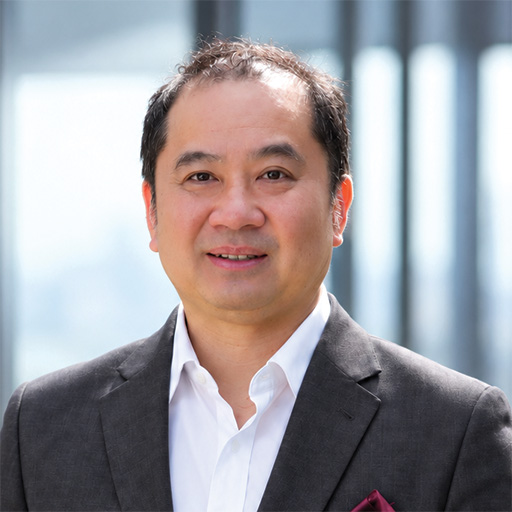
Director & Mortgage/ Credit Adviser
Access exclusive benefits, local partnerships and regular events designed to help you thrive.